Michael StanfordCFP® | Independent financial advisor, Denver Tech Center
I help small business owners build retirement plans that work for them and their team, help families build wealth and stay ahead financially, and help people nearing retirement turn savings into a reliable income.
Book a free 20-minute call Call 303-242-6326Three kinds of people I work with
I keep my practice focused so I can go deep on the decisions that matter most to these clients.
Small business owners
Your business is probably your biggest asset. Your retirement plan and your exit should be designed around it.
- 401(k) and Safe Harbor plan design for small businesses
- Strategies to increase owner contributions and reduce taxes
- Buy-sell agreements and business succession
- Exit planning before you sell
Small business 401(k) plan design and exit planning →
Families building wealth
The earlier you have a plan, the more choices you have later. Stay ahead of the curve instead of reacting to it.
- Cash flow and savings plans that fit your life
- Investing with purpose across 401(k)s, IRAs and brokerage accounts
- College savings and big goals like a home
- Tax-smart use of Roth and pre-tax accounts
Pre-retirees
The five to ten years before retirement are when the biggest, least reversible decisions get made.
- Retirement income and withdrawal order
- Roth conversions and Medicare (IRMAA) planning
- Pension decisions, including Colorado FPPA for police and fire
How working together starts
I work with clients in person in the Denver area and virtually in the states where I'm registered.
A free 20-minute call
Tell me what's on your mind. We'll see whether I'm the right fit, with no obligation.
Your plan
I gather your numbers and build a plan around your business, your taxes and your retirement date.
Ongoing guidance
We revisit the plan as your business, the tax code and your goals change.
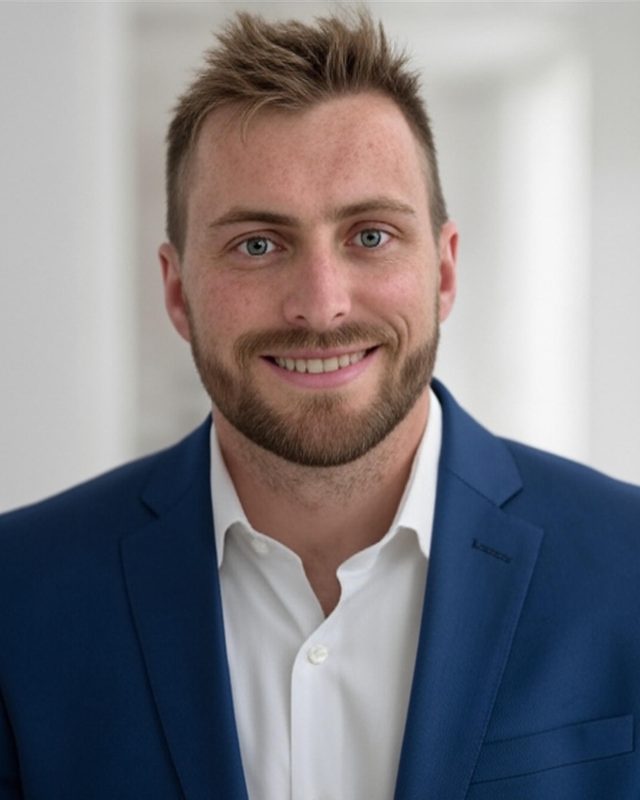
Why I do this work
Early on, I noticed that money stress is one of the quietest, most persistent sources of anxiety in people's lives, and that much of it is avoidable.
I watched smart, hardworking people make decisions that looked reasonable in the moment but quietly compounded into regret: overpaying taxes they didn't understand, taking on the wrong kind of debt, putting off investing because markets felt intimidating, or never connecting their day-to-day spending to the life they actually wanted. The gap wasn't intelligence or effort. It was clarity and a plan.
The moment I work for is when a client goes from “I hope this works out” to “I know exactly where I stand and what to do next.”
Financial planning lets me do both things I care about. I get to work through complex problems like tax efficiency, risk, cash flow and investment strategy, and then turn the answers into something that changes how someone sleeps at night and what becomes possible for them over the next 10, 20 or 40 years. I do love a good spreadsheet. But I do this work because I believe most people can reach better financial outcomes with the right plan, and I wanted the skills to help close that gap.
About Michael
I'm a CERTIFIED FINANCIAL PLANNER™ professional and independent financial advisor with Upstream Investment Partners in the Denver Tech Center, and a fourth-generation Coloradan from a family of farmers and entrepreneurs. I work with three groups: small business owners who want a retirement plan that does more for them and their team, families in their earning and saving years who want to stay ahead, and people approaching retirement who want a clear plan for income, taxes and their pension.
Why business owners, families and pre-retirees
As a fourth-generation Coloradan from a family of farmers and entrepreneurs, I grew up around business owners. I saw the rewards and the pressure firsthand: long hours, the blurred line between work and home, and decisions that affect the whole family. That's why I focus my financial planning practice on Denver-area business owners, families building wealth, and pre-retirees.
For business owners, that means balancing cash flow, growth and risk while building something that lasts. For families, it means a plan that keeps financial stress from stealing time and peace from the people who matter most. For pre-retirees, it means making the bigger decisions well: stepping back from a business or career, protecting what you've built, and moving from saving to spending with intention.
Whichever group you're in, my goal is the same: a plan that gives you more time back, reduces stress, and supports the family side of life, not just the financial side.
Outside of work
I'm a father of one, soon to be two, and I live in Parker with my family. You'll usually find me fishing, out in nature, or on family hikes and walks. Those outdoor rhythms feel like home, and they're how I stay grounded and present with my family.
Written and reviewed by Michael Stanford, CFP®. Last updated October 2026.
CFP® professional | Independent advisor affiliated with LPL Financial | Check my background on FINRA BrokerCheck
Choosing a financial advisor in Denver: the questions people search most
Straight answers to the questions people ask Google before they hire an advisor.
How do I find a good financial advisor near me?
Start by deciding what you need help with, then look for a local advisor who specializes in it. Check credentials such as the CFP® certification, look the advisor up on FINRA BrokerCheck, ask how they are paid, and meet before you commit. In the Denver area, Michael Stanford, CFP®, works from the Denver Tech Center with business owners, growing families and pre-retirees, and offers a free 20-minute call.
How much does a financial advisor cost?
Advisors are paid in a few common ways: a percentage of the assets they manage, a flat or subscription fee for planning, an hourly rate, or commissions on products. Some combine more than one. Whatever advisor you choose, ask for the total cost in dollars and what is included. Michael explains exactly how he is paid, in writing, before you decide to work together.
Is a financial advisor worth it?
It depends on how complex your situation is and how much time you want to spend managing it yourself. An advisor tends to add the most value around big decisions: setting up a business retirement plan, selling a business, changing jobs, choosing a pension option, managing taxes in retirement, or coordinating savings goals as a family grows. The free 20-minute call is a low-pressure way to find out whether advice is worth it for you.
When should I hire a financial advisor?
Common triggers are starting or growing a business, a new job, getting married or having children, receiving an inheritance, and the five to ten years before retirement. The earlier you have a plan, the more options you have.
What is a CERTIFIED FINANCIAL PLANNER™ (CFP®) professional?
A CFP® professional has completed coursework across financial planning, passed a comprehensive exam, met experience requirements, and agreed to CFP Board's ethics standards, including a duty to act in the client's best interest when providing financial advice. Michael Stanford holds the CFP® certification. You can verify any CFP® professional at cfp.net.
Is my financial advisor a fiduciary?
Ask directly, and ask which accounts the duty applies to. Investment advisory accounts are held to a fiduciary standard. Brokerage accounts are held to Regulation Best Interest. Michael will explain which standard applies to each account you hold with him.
What is an independent financial advisor?
An independent advisor is not employed by a bank, insurance company or fund company, so they are not tied to one company's products. Michael is an independent advisor with Upstream Investment Partners, affiliated with LPL Financial.
What questions should I ask before hiring a financial advisor?
Good questions include: What are your credentials? Who do you usually work with? How are you paid, in dollars? Are you a fiduciary on my accounts? What will you actually do for me each year? How often will we meet? You can also check any advisor's background on FINRA BrokerCheck.
How much money do I need to work with a financial advisor?
Many advisors set account minimums, so it is worth asking up front. The free 20-minute call is the easiest way to find out whether working together makes sense for you.
Free guides, sent to your inbox
Not ready for a call? Start with the guide that fits you.
Planning questions from business owners, families and pre-retirees
Short, plain answers. Every situation is different, so the free call is the best place to get specifics.
How do I set up a 401(k) for my small business?
Start by deciding what the plan needs to do: attract and keep employees, maximize what you as the owner can put away, or both. Then compare plan types (traditional 401(k), Safe Harbor 401(k), SIMPLE IRA, and for some owners a cash balance plan), pick a provider, and connect it to payroll. I help design the plan, choose the provider and keep you on track with your fiduciary responsibilities.
How do I pay less in taxes?
Most tax savings come from planning ahead rather than at filing time: using the right mix of pre-tax, Roth and HSA accounts, setting up a retirement plan that lets business owners save more, timing Roth conversions in lower-income years, managing investments to limit taxable gains, and planning withdrawals in retirement. I work alongside your CPA so your investment and retirement decisions support your tax plan.
Should I do Roth conversions before I retire?
Often the best window is the lower-income years between leaving work and starting Social Security or required minimum distributions. Whether it makes sense depends on your tax bracket now and later, Medicare IRMAA thresholds, and how you'd pay the tax. I model conversion amounts year by year so you can see the trade-off.
How do I plan for selling my business?
Ideally you start several years before a sale. That means understanding what the business is worth, putting a buy-sell agreement in place, coordinating with your CPA on the tax impact, and making sure your personal retirement plan doesn't depend on a single sale price. I work alongside your CPA and attorney on the planning side.
We're earning well but don't have a plan. Where do we start?
Start with where your money goes each month and what you want it to do: a home, college, financial independence, or all three. From there we decide how much to save, which accounts to use first (workplace 401(k), Roth or pre-tax IRA, 529, brokerage), and how to invest it. A plan in your earning years is what keeps you ahead instead of catching up later.
I'm a police officer or firefighter. What should I do with my pension?
Pension decisions such as Colorado FPPA benefit options, DROP and survivor elections are usually permanent, so they deserve careful review. I help first responders compare their options and build a retirement income plan around the pension.
Do you work with clients outside Colorado?
Yes. I work with clients virtually in the states where I'm registered. Reach out and I'll confirm whether I can work with you in your state.
What happens on the free 20-minute call?
You tell me what's on your mind, I ask a few questions about your situation, and we decide together whether working together makes sense. There's no cost and no obligation.
Book a free 20-minute call
Business owner, growing family or approaching retirement? Send me a note or call, and we'll find a time.
Schedule your free call- Phone
- 303-242-6326
- [email protected]
- Office
- 8101 E Prentice Ave Ste 775
Greenwood Village, CO 80111
(Denver Tech Center) Directions - Serving
- Denver, Parker, Centennial, Lone Tree, Castle Rock, and clients virtually in states where registered